The Day the Money Leaves Twice: How Refunds Quietly Drain a Retailer's Working Capital
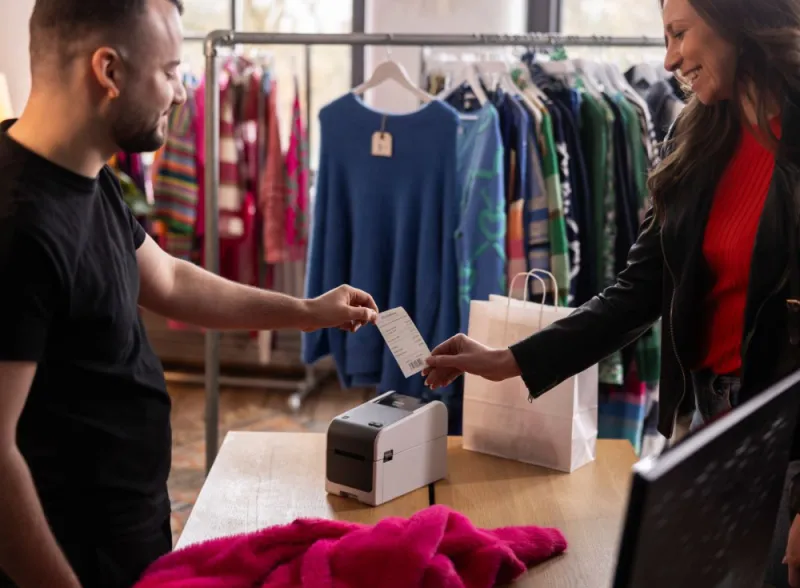
Photo: retail customer returning merchandise at store counter receipt, via d3clgxd6dhj3d0.cloudfront.net
There is a moment in late January that most US retail finance teams know well: the returns flood in, the refund queue fills, and the bank balance starts moving in a direction nobody budgets for. Refunds are treated as a customer-service line item, a cost of doing business. What gets missed is the mechanical reality underneath — that a refund is not simply a reversal. It is a new transaction, and the original one's costs do not politely undo themselves.
The Asymmetry Nobody Explains
Here is what actually happens when a $100 sale is refunded. The customer's money typically returns within three to ten business days, depending on the card network and the merchant's processor. But the interchange fee paid on the original transaction — often 1.5% to 2.5% of the sale — is frequently not credited back. Some acquiring banks and processors return interchange on refunds; many do not, or do so only partially, or only when the refund occurs within a narrow window.
Layer on top of that the fixed per-transaction fee, which almost never returns, and any fixed monthly or statement fees that continue regardless. On a $100 refund, the merchant may recover $97 or less — and on high-volume return categories like apparel, where return rates can exceed 25%, those leaked percentages accumulate into a serious annual figure.
The Timing Trap
The fee leakage is only half the problem. The other half is timing.
Refunds frequently leave the merchant's account — or the processor debits the pending settlement — before the original sale's funds have fully landed. During a return spike, a retailer can be refunding money it has not yet received, creating a short-term liquidity squeeze that looks irrational on paper: sales were strong in December, yet January's bank balance is thin.
This is compounded by chargeback dynamics. A disputed transaction ties up the disputed amount plus a chargeback fee for weeks while the case is adjudicated. A return-season spike in disputes therefore produces a parallel spike in frozen capital, at precisely the moment a retailer is placing spring inventory orders.
Modeling Your True Refund Cost
Most merchants can state their return rate. Very few can state their refund cost per return. A more honest calculation includes:
- Non-recouped interchange on the original transaction
- Fixed per-transaction fees that do not reverse
- Processor refund-handling rules, including any refund windows or fees
- Chargeback fees on returns that escalate to disputes
- The float cost of refunds issued before original settlements clear
- Reverse logistics and restocking labor, which sit outside the payment stack but belong in the same decision
Run this across a full year of transactions and the number usually surprises people. It also reframes return-policy design: a store credit option, for instance, avoids the payment-rail costs entirely while keeping the cash inside the business — a detail worth more than most loyalty discounts.
What Merchants Can Actually Do
First, read the refund language in your processor agreement. Interchange recoupment policy varies widely and is negotiable at volume. Second, tighten refund windows where your return data supports it — every day of eligibility is a day of fee exposure. Third, monitor refund-to-transaction ratios by product line; processors watch these ratios for fraud signals, and an unexplained spike can trigger reserves or holds on your entire account, which is a far worse cash-flow event than the refunds themselves.
Fourth, time your refund batch processing deliberately. Issuing refunds after the day's settlement clears, rather than in real time, smooths the liquidity dip without affecting the customer's experience in any meaningful way.
Returns are not going away, and they should not — a generous return policy earns loyalty that compounds. But the plumbing beneath those returns deserves the same scrutiny as any other cost center. The money will leave. The question is how much of it leaves twice.